
Boeing Open Enrollment Ends November 20: Higher Premiums, a Bigger HSA Limit, and a Medicare Decision
THE SHORT VERSION
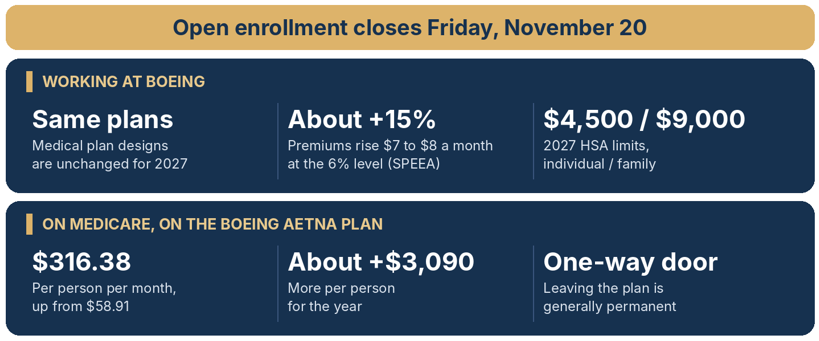
- Open enrollment ends Friday, November 20. Changes take effect January 1, 2027.
- Working employees: same plans, higher premiums. About 15% more, or roughly $7 to $8 a month at the 6% contribution level for SPEEA Prof and Tech members.
- The HSA is one of the most overlooked retirement planning tools we see. The 2027 limits rise to $4,500 for an individual and $9,000 for a family.
- Boeing Aetna Medicare plan: the premium rises to $316.38 per person per month, up from $58.91. That is about $3,090 more per person for the year.
- Leaving the Medicare plan is generally permanent. Evaluate the alternatives carefully before making a change.
Most years, open enrollment is a quick check of last year’s elections. This year a few changes deserve a closer look, and one is a major decision for retirees on the Boeing Aetna Medicare plan.
If you are working at Boeing
The medical plans themselves are not changing for 2027. What you pay for them is. The figures here come from SPEEA’s materials for Prof and Tech members. Non-union and other groups have different rates, so check your own numbers in the Total Rewards portal. Employee premiums are up about 15%. In SPEEA’s examples, the 6% contribution level on the Advantage+ plan goes from $45.77 to $52.69 a month, about $7 more a month or $83 more for the year. The 6% level on the Traditional plan goes from $49.36 to $56.87, about $8 more a month or $90 more for the year. New for 2027: fertility and doula coverage, and a new vision network (VSP replaces Davis).
Advantage+ or Traditional?
This is the main choice for most working employees. Both plans pay 90% of in-network costs after the deductible. The differences are what you pay each month, how much you pay before the plan starts paying, and whether you get a Health Savings Account.
| Advantage+ | Traditional | |
| Monthly premium, employee only | $0 to $79.03 | $56.87 to $113.74 |
| Deductible, individual / family | $1,750 / $3,500 | $300 / $900 |
| Out-of-pocket maximum, in network | $3,500 / $7,000, prescriptions included | $2,000 / $4,500, prescriptions separate |
| Boeing HSA contribution | $875 / $1,750 | None |
Source: SPEEA’s 2027 open enrollment materials for Prof and Tech members. Premiums depend on your pay tier.
The trade-off with Advantage+ is the higher deductible. Boeing’s HSA contribution covers half of it, and the premiums are lower, so the gap is smaller than it first looks.
- Advantage+ tends to fit if you are generally healthy, can cover the deductible from savings or the HSA, and want to build the HSA as a retirement account.
- Traditional tends to fit if you expect regular care or ongoing prescriptions, want more predictable costs when you use care, or a $1,750 deductible would strain your cash flow.
Either way, compare both plans against a typical year and a high-cost year. If you use a Flexible Spending Account, only a limited amount carries over to the next year (SPEEA’s materials show $680), and employees earning more than $160,000 have a lower dependent care limit.
Why the HSA deserves a closer look
If you choose Advantage+, make sure you put the HSA to work toward your financial goals. It is only available with Advantage+, and it is one of the most overlooked retirement planning tools we see. It is the only account with three tax benefits: contributions are not taxed going in, growth is not taxed, and withdrawals for qualified medical costs are not taxed coming out. Used the right way, it can support your retirement picture:
- Fund it. For 2027 the limit is $4,500 for an individual and $9,000 for a family, and Boeing’s contribution counts toward that limit. At 55 or older you can add another $1,000, and a spouse who is also 55 or older can add $1,000 through an HSA of their own.
- Invest it, and leave it alone if you can. The balance rolls forward every year and stays yours after you leave Boeing. If cash flow allows, pay current medical costs out of pocket and let the HSA stay invested for retirement.
- Use it in retirement. At 65 or older, HSA dollars can generally pay Medicare premiums tax-free, including Part B, Part D, and Medicare Advantage premiums such as the Boeing Aetna plan. Medigap premiums do not qualify.
- Plan the Medicare handoff. HSA contributions generally have to stop once Medicare coverage begins, and Part A can be backdated up to six months when you enroll after 65.
More on this: The Boeing HSA: A Commonly Missed Retirement Opportunity
If you are on Medicare and the Boeing Aetna plan
If you are 65 or older and on the Boeing Aetna Medicare plan, we recorded a short video that walks through the 2027 changes in more detail:
What we know
The 2027 premium is $316.38 per person per month, or $632.76 for a retiree and spouse, on top of the Medicare Part B premium. In 2026 it was $58.91, and in 2024 and 2025 it was $0. That is about $257 more per month, or roughly $3,090 more per person for the year. Elections are due November 20. If you do nothing, you stay enrolled at the new premium.
According to SPEEA, the $0 premium came from an agreement with Boeing covering 2024 through 2028. It allowed a premium if Aetna determined there were material legislative, regulatory, or funding changes, and that provision was used for 2026 and again, to a much larger degree, for 2027. Further increases are possible.
How the plan compares now
At the old price, this plan was about as close to a no-brainer as these decisions get. That is no longer the case. As far as we can tell, the plan design itself is unchanged: in 2026 it capped covered medical costs at $800 a year and covered drug costs at $2,100 a year, with drug coverage built in. Medicare’s standard drug cap rises to $2,400 for 2027, so confirm the 2027 figures in your plan documents.
The natural comparison is a Medicare supplement such as Plan G. With Plan G you can see any provider nationwide that accepts Medicare, and after a small annual deductible it generally pays in full. You add a separate Part D drug plan, and you give up extras a Medicare Advantage plan may include, such as fitness and hearing benefits. Washington quotes we have seen recently for Plan G run roughly $280 to $300 a month, though premiums vary by carrier and age. If you do not need comprehensive coverage, there are lower-cost options that could save meaningfully more.
What to confirm before you change anything
- Whether you can get a Medicare supplement without health questions. Guaranteed-issue rights depend on your circumstances, the rules that apply, and timing. A licensed Medicare professional we work with tells us retirees leaving Boeing’s plan qualify, but federal rules do not guarantee that for everyone who leaves employer coverage voluntarily. Confirm your own eligibility and have the replacement coverage approved before you leave.
- That you are comfortable not coming back. Leave the Boeing plan and you generally cannot return, with only narrow exceptions.
- A younger spouse’s coverage. If your spouse is under 65 and on Boeing retiree coverage, that coverage generally depends on you staying enrolled.
- Your prescriptions. A standalone drug plan has its own list of covered drugs, and its annual out-of-pocket cap only applies to drugs on that list.
- Your doctors at UW Medicine. UW Medicine’s website lists Aetna Medicare Advantage as out of network starting February 19, 2027. We have not confirmed whether that applies to the Boeing plan, so ask UW Medicine and Aetna.
Staying for 2027
This is a big decision on a short timeline. Because leaving is generally permanent, many of the retirees we work with are staying on the Boeing plan for 2027 and using the year to compare options. That is a reasonable choice, but it is not the right one for everyone. Staying means paying the higher premium for a full year, and your health and the enrollment rules can change before you decide again. Confirm your options now, even if you plan to stay.
The bottom line
For most working employees, this is a 15-minute review: same plans, higher premiums, and an HSA worth using well. For retirees on the Boeing Aetna Medicare plan, it is a bigger decision with lasting consequences, and it deserves a careful look at your health needs, your doctors, and your budget. We work through these decisions with Boeing families every year. If you would like a second opinion on how these decisions fit into your overall retirement plan, happy to help if it would be useful.
Schedule a Complimentary Strategy Session
team@stablerwm.com | (425) 646-6327
Securities and Advisory services are offered through LPL Financial, a registered investment advisor. Member FINRA/SIPC. Stabler Wealth Management is not registered as a broker-dealer or investment advisor.
No strategy assures success or protects against loss. Stabler Wealth Management and LPL Financial are not affiliated with or endorsed by Boeing.
This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific tax issues with a qualified tax advisor.
This presentation was created for educational and informational purposes only and is not intended as ERISA, tax, legal or investment advice. Securities and advisory services offered through LPL Financial, Member FINRA/SIPC.
Category
Stay Informed
Join our mailing list to receive monthly newsletters with information that impacts your financial decisions.
Certified Financial Planner
In Business 35+ Years

Microsoft Specialists
