
Year-End Moves for Microsoft Professionals, Including Navigating the Voluntary Exit Offer
THE SHORT VERSION
- The voluntary exit offer is this year’s biggest year-end decision. Decisions are due in early December with a December 31 exit date, inside the same window as every other deadline in this article.
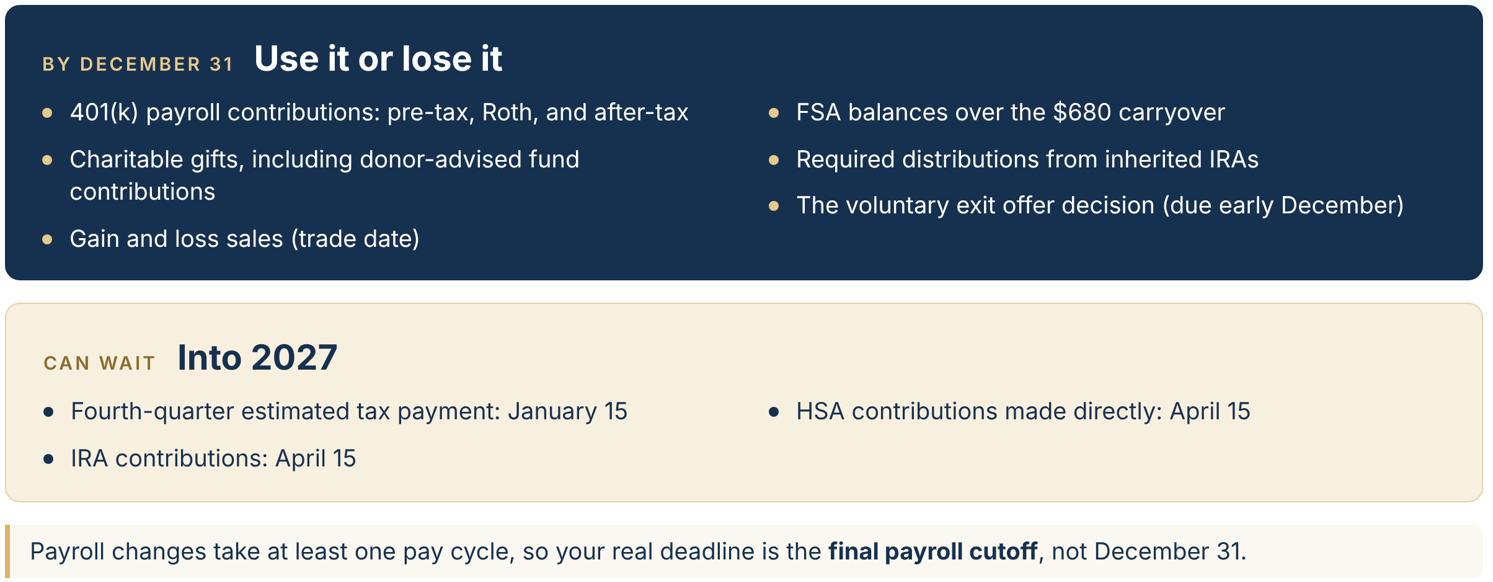
- Many planning items carry a hard year-end deadline. Payroll contributions, charitable gifts, and gain or loss sales lock to the calendar year, and elections take a payroll cycle to land.
- Your 401(k) room does not roll over. $24,500 of deferrals, the catch-up if you are 50 or older, and up to $35,250 of after-tax Mega Backdoor Roth space all reset in January.
- The 22% withholding is probably not your rate. Each RSU vest quietly adds to an April balance due; December is when the fix still works.
- New rules this year. A 0.5% of AGI floor on itemized charitable deductions and a 35% cap on the benefit for top-bracket filers reward bunching and appreciated-stock gifts.
*You may also want to watch our recent webinar: Year-End Financial Moves for Microsoft Professionals
This year’s biggest year-end decision arrived by email
On October 26, Microsoft announced a voluntary exit offer that reports put at roughly 60,000 employees, about a quarter of the company, across the U.S., Canada, the U.K., and India. Participation varies by organization and level, and eligible employees received their individual terms by email. Our understanding at this point: the package follows Microsoft’s standard severance structure, with base pay based on tenure and level, continued stock vesting for a period, and healthcare coverage for a fixed window, without the extended healthcare option the spring retirement program carried.
Two things are worth saying plainly. First, receiving an offer does not mean your role is going away. This is a choice, and for many people the right answer will be to stay. Second, decisions are due in early December with a December 31 exit, which does not leave a lot of time to evaluate the best decision for you, and it puts the choice inside the same window as every other move in this article.
We will share more as the terms become clearer. For now, if you received an offer, the items to review for your own picture: which tax year the severance and final vests would land in, how your healthcare bridges toward Medicare, what happens to your stock vesting, and whether unemployment benefits would apply, which should not be assumed either way under Washington’s updated rules; confirm your situation with the Employment Security Department. And if you accept, your final paychecks are the last chance to use this year’s 401(k) and Mega Backdoor Roth room, which brings us to the moves themselves.
The year-end window: now through December 31
Your RSUs vest quarterly: February, May, August, November. Each vest is a checkpoint, and the same playbook applies at every one: decide what to sell, decide what to fund, and check your withholding. The November vest, with shares arriving at the beginning of December, is simply the last checkpoint before the deadline, which is why it carries the year.
What follows is the five-move checklist we run with Microsoft clients each year, in order of dollars at stake. Most moves take one payroll change or one phone call.
Move 1: Top off your 401(k)
For 2026 you can defer $24,500, plus an $8,000 catch-up at 50 and older, or $11,250 if you turn 60 through 63 this year. New this year: if your prior-year Microsoft wages were $150,000 or more, catch-up contributions must be made as Roth. In most cases we see, the catch-up remains well worth doing; those dollars now build your tax-free bucket.
Microsoft matches 50 cents on every pre-tax or Roth deferral dollar, up to $12,250, and the match accrues as you contribute. After-tax dollars draw no match, which is why deferrals come first. Check your pace on Fidelity NetBenefits and spread any remaining gap across your final paychecks.
Move 2: Fill the Mega Backdoor Roth
The all-in 2026 limit is $72,000. After your deferrals and Microsoft’s match, up to $35,250 of after-tax room remains, and a single dropdown election converts it to Roth automatically. Unused room does not roll over. With the catch-up, the all-in limit rises to $80,000 at 50 and older, or up to $83,250 if you turn 60 through 63 this year. Selling shares from the November vest and raising your payroll percentage for the final cycles is the standard way to fill it late in the year. We went deep on this strategy in September; the webinar replay is linked above.
Considering the exit offer? This move compresses: whatever room you want to use has to fit in the paychecks remaining before your exit date.
Move 3: The RSU withholding checkup
Microsoft withholds a flat 22% federal on RSU income (37% only above $1 million of supplemental wages). Most vesting-stage professionals sit in higher brackets, so each vest adds to an April balance due. Two fixes still work in December: raise withholding on your final paychecks, since withholding is treated as paid evenly through the year, or make a fourth-quarter estimated payment by January 15. Covering 110% of last year’s total tax generally stops underpayment penalties at higher incomes.
Considering the exit offer? Run the projection both ways. Severance, final vests, and a mid-career income change can move you across brackets, and the 2026 versus 2027 comparison is where the planning value usually sits.
Move 4: Harvest gains and losses on purpose
Realized losses offset gains, then up to $3,000 of ordinary income, with the wash-sale rule in mind. Gain harvesting can also make sense: trimming concentrated Microsoft stock in a year when your rate is reasonable. In Washington, a December sale carries a second layer: 7% on long-term gains above the state deduction ($278,000 in 2025; the 2026 amount is pending from the Department of Revenue), and 9.9% above $1 million. December versus January timing on a large sale can change the result twice.
Considering the exit offer? Lower-income years after a transition can open unusually favorable windows for gain harvesting and diversification. That possibility belongs in the decision, not just the aftermath.
Move 5: Giving under this year’s new rules
2026 is the first year end under the new charitable rules. Itemizers can deduct only the gifts above 0.5% of adjusted gross income, for taxpayers in the 37% bracket new limitations effectively cap the federal tax benefit of itemized deductions at 35%, and non-itemizers gained a deduction of up to $1,000 ($2,000 filing jointly) for cash gifts. The response we see working: bunch several years of giving through a donor advised fund, and give appreciated Microsoft shares rather than cash, which addresses concentration and giving in one move.
The bottom line
Most of these moves come down to a payroll change or a single trade. What they share is the calendar: your final payroll cutoff, December 31 for gifts and trades, January 15 for the final tax payment. And if the exit offer is on your desk, that same window decides it.
If you want help sorting out which of these apply to you, this is exactly what we cover in a complimentary year-end review: your 401(k) elections, a tax projection, your RSU and ESPP plan, and the exit offer if you received one. We are setting aside time over the next few weeks, and I would suggest grabbing a spot while it is top of mind.
Contact Us:
team@stablerwm.com | (425) 646-6327
Stabler Wealth Management and LPL Financial are not affiliated with or endorsed by Microsoft. This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific tax issues with a qualified tax advisor.
Securities and Advisory services are offered through LPL Financial, a registered investment advisor. Member FINRA/SIPC. Stabler Wealth Management is not registered as a broker-dealer or investment advisor.
Hypothetical figures are for illustration only and do not represent the performance of any specific investment.
Category
Stay Informed
Join our mailing list to receive monthly newsletters with information that impacts your financial decisions.
Certified Financial Planner
In Business 35+ Years

Microsoft Specialists
